Broadening Delivered. Now Prepare for Volatility : Franklin Templeton
we published “Get ready for a broader US equity market,” arguing that the extraordinary concentration in US mega-cap technology stocks was unlikely to persist indefinitely. While the Magnificent Seven1 had become the dominant driver of market returns, we believed improving fundamentals across a much broader set of companies, sectors and regions would eventually support a healthier and more diversified bull market. One year later, in January 2026, we expanded on that framework in “Broadening momentum: From US technology leadership to US small-caps and emerging markets,” moving from the broad idea of improving market breadth to identifying where we believed leadership would emerge: US small-caps, equal-weighted equities and emerging markets. The past 18 months have largely validated that view. Rather than continuing to rely on an increasingly narrow group of mega-cap technology stocks, investors have been rewarded across a much wider opportunity set. Leadership has broadened across market capitalizations, investment styles and global equity markets, with the MSCI Emerging Markets (EM) Index returning 62%, Russell 1000 Value Index 40% and Russell 2000 Value 39%, all comfortably outperforming the Magnificent Seven (25%) over the same period. Today, however, investors face a different challenge. The broadening bull market remains intact, but after a powerful recovery from the March lows, markets are entering a more demanding phase. Earnings continue to provide strong support, yet liquidity2 is becoming less accommodative, market leadership is becoming increasingly selective and volatility is likely to increase.
The Broadening We Expected Has Arrived
At the end of 2024 and 2025, we argued in our papers referenced above that a broadening of leadership away from the Magnificent Seven would characterize the next phase of the bull market. Rather than expecting mega-cap technology to continue carrying the market indefinitely, we highlighted improving opportunities in US small-caps, equal-weighted equities, value and emerging markets. Earnings power was broadening and we believe that stocks ultimately follow earnings growth. That is precisely how past 18 months have unfolded.
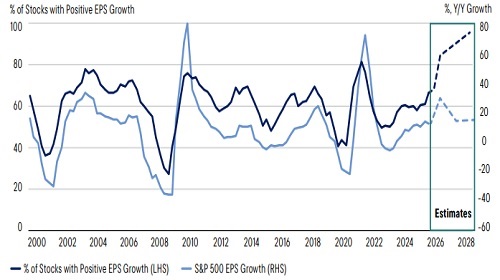
Sources: FactSet, S&P Dow Jones Indices, FactSet Market Aggregates; analysis by Franklin Templeton Institute. From Q4-2000 to Q4-2028 E=estimated. Updated as of July 31, 2026. There is no assurance that any estimate, forecast or projection will be realized. Note: Right Y-axis scale is truncated. Important data provider notices and terms are available at www.franklintempletondatasources.com. Over the past 18 months, the Magnificent Seven returned approximately 25%, compared with roughly 34% for the Russell 2000, 62% for emerging markets and 40% for the Russell 1000 Value index. Rather than collapsing under the weight of weaker mega-cap performance, the market found new leadership.
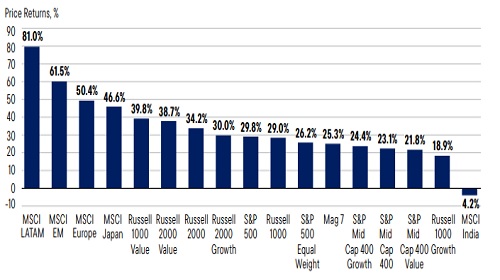
Sources: FactSet, MSCI, Russell Indices, S&P Dow Jones Indices. Analysis by Franklin Templeton Institute. Performance from December 31, 2024, to July 31, 2026. Indexes are unmanaged and one cannot invest directly in an index. Indexes do not include fees, expenses or sales charges. Past performance is not an indicator or guarantee of future results. Important data provider notices and terms are available at www.franklintempletondatasources.com.
our previous paper. Our historical analysis showed that geopolitical shocks have generally created temporary drawdowns rather than permanently impaired equity returns. The explanation is surprisingly straightforward. Over the long run, our research has found that equity markets are driven far less by geopolitical events than by the relationship between economic growth, corporate profits and investor expectations. Elections, conflicts and policy announcements influence markets over weeks or months. Earnings determine returns over years.
Above views are of the author and not of the website kindly read disclaimer