Quote on FPI Flows in Indian Markets for the week of 2–6 November 2026 by Dheeraj Gaur, Chief Investment Strategy Officer at Choice Wealth
Below the Quote on FPI Flows in Indian Markets: for the week of 2–6 November 2026 by Dheeraj Gaur, Chief Investment Strategy Officer, Choice Wealth
From nine weeks of selling to the biggest week of FPI buying in years. One election, one oil slump and one AI wobble later, the Nifty is back at 25,000.
Equity Flows: Foreigners did not just return, they returned in size
Last week we asked whether FPIs would keep buying. They did, and then some. On provisional NSE numbers, FPIs bought rs 3,115 crore on Monday, Rs 6,837 crore on Tuesday, Rs 7,284 crore on Wednesday, rs 14,975 crore on Thursday and rs 13,750 crore on Friday. Net, about Rs 45,960 crore of buying in a single week – more than the entire rs 45,160 crore of selling that FPIs did through October on provisional data. Thursday’s purchase was the biggest single-day net buy in nearly six years. DIIs, who had spent weeks absorbing foreign selling, flipped to net sellers of about rs 24,200 crore.
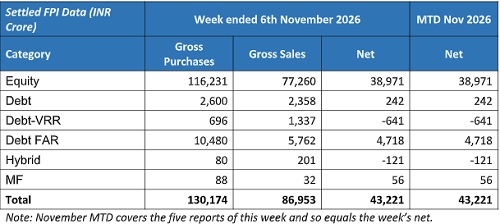
The settled numbers agree. The week’s five custodian reports show FPIs as net buyers of about rs 38,971 crore in equities – roughly rs 4,458 crore on Monday, rs 3,352 crore on Tuesday, rs 7,053 crore on Wednesday, rs 7,830 crore on Thursday and a huge rs 16,278 crore on Friday. Unlike last week, this was not a Jio story: only about rs 452 crore came from the primary market, so roughly Rs 38,500 crore was plain secondary-market buying.
A big swing! After an October that closed at about –rs 34,843 crore on a settled basis, November has started at about +Rs 38,971 crore. Calendar-2026 outflows are now down to roughly rs 2.56 lakh crore.
For the detail-minded:
So, what changed this week?
Three things lined up. First, politics and oil: the US midterm results were read as raising the odds of a de-escalation in the US–Iran conflict, and Brent fell about 13% to roughly $98 – its steepest weekly drop since the start of Covid. Cheaper oil is the single biggest relief for India’s inflation, current account and rupee and the rupee strengthened to about Rs 93.90 per dollar from around rs 95.4 a week ago.
Second, the AI trade cracked. A tech rout on Thursday took the Nasdaq down 5.5% and the S&P 500 4.4%, after weak Qualcomm results and worries about slowing AI-infrastructure spending, and Korea and Japan fell about 6% on Friday. Global funds have been rotating out of AI-linked names into markets like India, which has little AI exposure – Indian IT stocks even rose. And third, India simply looked cheap after a poor year, with earnings holding up.
The result: the Nifty rose 8.6% to 25,030 and the Sensex 8.8% to 81,028, their best week since February 2021 and a seven-session winning streak, the longest for the Nifty in 14 months. Banks and autos led, with ICICI Bank up 4.3% on Friday alone. The rally has been narrow, though: more shares fell than rose on Friday and the small-cap index slipped 0.8%. And even after this week, the Nifty is still down about 4.2% for the year, against a 7% gain for MSCI Emerging Markets.
In short: a week ago FPIs were buying a few bricks; this week they bought the building.
Debt Flows: FAR joins the party
Debt flows turned around too, but in just one lane. Across the week’s reports, FPIs bought about rs 4,718 crore through FAR, and almost all of it came at the end of the week – rs 2,543 crore on Thursday’s report and rs 2,669 crore on Friday’s. The general limit added a modest rs 242 crore, while VRR saw net selling of about Rs 641 crore. Put together, debt was a net inflow of roughly Rs 4,320 crore, after FAR lost about rs 6,986 crore in October.
Cheaper oil, a steadier rupee and a much stronger currency are exactly the ingredients FAR investors have been waiting for and with yields still near multi-year highs, the carry is attractive. Whether the buying lasts will depend on how the rupee and the Fed behave.
Is this the turn – or a trade?
No doubt a very good week, with a few loose ends.US data: Friday’s October jobs report was much stronger than expected, at about 165,000 payrolls against roughly 65,000 forecast, with unemployment down to 4.1%. The 10-year Treasury yield rose to about 4.87% (still below the roughly 5.0% of a week ago), the dollar index jumped 0.7% to about 102.2, and the odds of a December Fed hike moved back to roughly 70–80%. Oil is lower but still near $100, and any hiccup in Iran talks could reverse it. Breadth is thin, and seven straight up-sessions usually invite some profit-booking: Gift Nifty pointed to a lower open on Monday. And a week of Rs 46,000 crore of buying is hard to repeat.
The silver lining, if you want one: this is the first time in months that the global backdrop, oil, the rupee and flows have all pointed the same way. The question is for how long.
What to watch next week?
A short, festive week: Muhurat trading on Sunday, 8 November (2:20–3:30 pm), then regular sessions on Monday, Wednesday, Thursday and Friday, with markets closed on Tuesday, 10 November for Diwali-Balipratipada. What will matter for FPI flows:
* US CPI on Tuesday, 10 November. With a December hike nearly priced in, a hot print could push yields and the dollar higher.
* Brent and the Gulf. Does oil hold below $100 or does the de-escalation story stall?
* The rupee. Whether USD/INR holds around rs 94 or better, and what the RBI does with its liquidity measures.
* Fed speakers and US yields. After the jobs report, any hawkish messaging on a December hike will be watched closely.
* Domestic earnings and breadth. More Q2 results are still to come and while the earnings have been encouraging, the market needs mid- and small-caps to join the large-cap rally.
Bottom Line:In just a week FPIs wiped out a whole month of selling – about rs 45,960 crore of provisional buying and about rs 38,971 crore on a settled basis, almost all of it secondary-market. Cheaper oil, a stronger rupee and a rotation out of AI did the heavy lifting. The test now is whether the buying survives a stronger US labour market, a possible December Fed hike and a very stretched seven-day run.
The views are personal. Data points are referenced from publicly available information, internal sources and other third-party sources believed to be reliable. While every care has been taken to ensure veracity of data, however, the writer cannot guarantee the accuracy of such information, assure its completeness, or warrant that such information will not be changed. The information in this report may include inaccuracies or typographical errors.
Above views are of the author and not of the website kindly read disclaimer
Tag News
Quote on Bank Nifty 06th November 2026 by Vatsal Bhuva, Technical Analyst at LKP Securities
More News
Quote on FPI flows 07.11.2026 from Dr. V K Vijayakumar, Chief Investment Strategist, Geojit ...